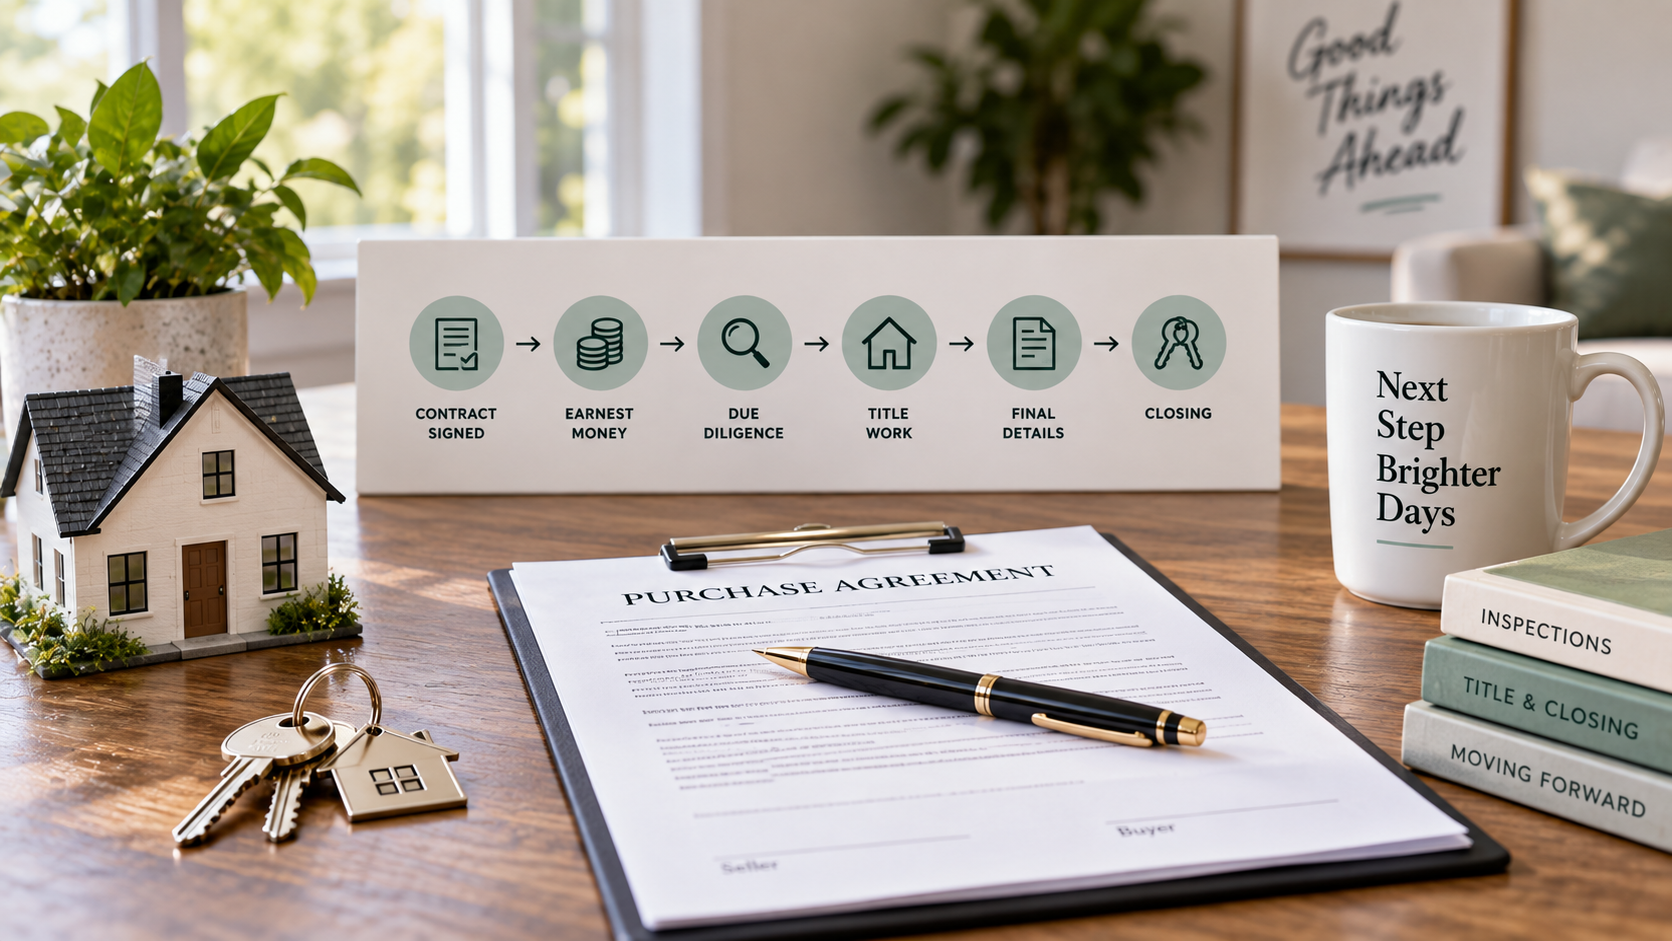
Signing the Offer Starts the Transaction. It Does Not Finish It.
For many sellers, accepting an offer feels like the major decision has been made. The price has been agreed to, the buyer has committed to moving forward, and there is finally a clear path toward closing. That is an important milestone, but it is not the end of the transaction. Once the agreement is signed, the work shifts from deciding whether there is a deal to making sure the deal can actually close.
The period between contract and closing is where the buyer confirms information about the property, title is reviewed, earnest money is handled, documents are gathered, and any issues that could interfere with the sale are identified. Depending on the transaction, there may also be inspections, repair estimates, financing requirements, occupancy questions, probate matters, liens, or other details that need to be resolved before ownership can transfer.
At REWholesalers, we believe transparency should not begin after a contract is signed. By the time a seller accepts an offer, they should already understand the major parts of the transaction, including what due diligence remains, whether assignment is possible, what access may be needed, where earnest money will be held, and what still has to happen before the property is actually sold.
The Purchase Agreement Becomes the Roadmap
Once both sides sign the purchase agreement, the transaction begins operating according to the terms of that contract. The agreement should spell out the purchase price, closing date, earnest money, due diligence rights, access to the property, closing costs, title requirements, and any other conditions that affect the sale. If the buyer has the right to assign the agreement, that should also be addressed clearly.
This is why the contract matters just as much as the offer price. Two buyers can offer the same amount and create very different transactions depending on their terms. One may require a long inspection period, financing contingency, appraisal, and several conditions before closing. Another may have a shorter due diligence period and fewer financing-related requirements. A seller should understand those differences before deciding which offer actually fits.
Earnest Money and Due Diligence Usually Begin Early
Many real estate agreements require the buyer to deposit earnest money shortly after the contract is signed. That money is generally held by a neutral third party, such as a title company, attorney, escrow company, or other closing professional, depending on the state and the structure of the transaction. The contract determines the amount, deadline, and circumstances under which the deposit may be refundable or nonrefundable.
The size of the earnest money deposit does not automatically tell a seller whether a buyer will close, but the details still matter. Sellers should know where the money is being held, when it is due, and what happens to it if the transaction does not close. Those points should not be vague.
At the same time, the buyer usually begins due diligence. This is the period when the buyer confirms the assumptions behind the offer by reviewing the property in more detail. That may include walking the property again, estimating repairs, reviewing leases, confirming occupancy, checking utilities, researching zoning, reviewing permits, verifying property details, or evaluating anything else that could affect ownership, resale, or the buyer’s intended use.
An investor buyer may focus heavily on condition, construction costs, rental potential, and the realistic exit strategy for the property. A retail buyer may be more focused on inspections, financing, appraisal, and whether the property is suitable as a home. The important point is that accepting the offer does not usually mean the buyer stops evaluating the property.
Inspections Are Not Always About Asking the Seller to Make Repairs
The word “inspection” can create unnecessary anxiety for sellers because it often brings to mind a long list of repair demands. That can happen in some traditional retail transactions, but not every inspection serves the same purpose.
An investor may inspect the property simply to understand what work will be required after closing. A contractor may walk the property to estimate renovation costs. A buyer may want a closer look at the roof, foundation, electrical system, plumbing, HVAC, or other major components to make sure there are no conditions that materially change the original assumptions.
If the property is being sold as-is, the seller may not be agreeing to make repairs at all. The buyer may still inspect because buying as-is does not mean buying without understanding what is there. The contract should make clear what rights the buyer has, how long those rights last, and what happens if significant new information is discovered.
Due Diligence Should Confirm the Deal, Not Create an Excuse to Renegotiate It
There is an important difference between discovering genuinely new information and using the due diligence period to renegotiate a property that was already understood when the offer was made. If a buyer could reasonably see the dated kitchen, old flooring, worn roof, overgrown yard, or other obvious condition before making the offer, those items should already have been considered.
Due diligence should help confirm the transaction, not become a routine strategy for getting a seller under contract and then looking for reasons to lower the price afterward. That does not mean an offer can never change. Sometimes a significant condition is discovered that neither side knew about when the agreement was signed, and that new information can legitimately affect the economics of the transaction.
A major foundation problem, unexpected title issue, serious septic failure, undisclosed tenant situation, or another material condition may require another conversation. When that happens, the buyer should be able to explain what changed, why it matters, and how it affects the original assumptions behind the offer. A vague request for a price reduction is not the same thing as a clear explanation.
Title Work Happens While the Property Is Being Evaluated
While the buyer is completing due diligence, the closing professional is typically reviewing ownership and title. That process is designed to confirm that the seller can transfer clear title to the buyer at closing.
The title search may uncover existing mortgages, unpaid taxes, liens, judgments, ownership discrepancies, probate issues, divorce-related interests, old unreleased loans, or other matters that need to be addressed before the property can transfer. Many of these issues are routine and can be resolved as part of the closing process, while others take additional time.
A seller may not know an old mortgage release was never properly recorded until the title company finds it. An inherited property may require additional probate documentation. Multiple owners may need to sign. A lien may need to be paid from closing proceeds. These are some of the reasons a transaction can take longer than expected even when both buyer and seller are fully committed to closing.
The Closing Company May Need Information From the Seller
Sellers should expect to provide documentation during the closing process. The exact requests vary, but the title company, attorney, or escrow professional may ask for identification, mortgage information, payoff details, trust documents, probate records, entity documents, marital information, forwarding addresses, or other items needed to prepare the closing.
Responding quickly can help keep the transaction moving, particularly when there is an existing loan and the closing company needs time to obtain an official payoff statement. If there are multiple owners, trusts, estates, LLCs, or other entities involved, the documentation may be more extensive. The earlier those issues are identified, the easier they are usually to manage.
The Buyer May Need Access to the Property More Than Once
Another thing sellers may not expect is that the buyer may need additional access before closing. A contractor may need to review repairs, an insurance provider may need information, a lender may require access, an appraiser may need to visit, or the buyer may want to complete a final walkthrough before closing.
In an investor transaction, there may also be additional people evaluating the property as part of the buyer’s closing plan. That does not mean a seller should be expected to provide unlimited access at any time. The contract should govern access, and visits should be coordinated reasonably.
What matters is that the seller understands in advance that signing the agreement does not always mean nobody else will visit the property until closing day.
Sometimes New Information Changes the Deal
A transaction is usually based on the information available when the offer is made. If materially different information appears during due diligence, the parties may need to have another conversation.
For example, a buyer may discover a significant structural problem that was not visible during the original evaluation. Title may reveal an unexpected lien. A tenant situation may be different from what was understood. A septic system, roof, electrical system, or other major component may require substantially more work than expected.
That does not mean every new issue should result in a lower offer. Minor repairs and ordinary imperfections are part of buying real estate, and a buyer should not use every small discovery as an excuse to renegotiate an agreement. But genuinely significant information can change the economics of a transaction.
When that happens, we believe the conversation should be specific. The seller should hear what changed, why it matters, and what options remain. That may mean keeping the deal exactly as agreed, modifying the terms, moving the closing date, or deciding that the transaction no longer makes sense. A difficult conversation is better than a disappearing buyer.
Financing Can Add Another Layer
If the transaction involves conventional financing, the buyer may also be working through underwriting while everything else is happening. The lender may order an appraisal, verify the buyer’s finances, review the property, request additional documentation, and issue conditions that must be satisfied before funds are released.
That process can create delays even when the buyer fully intends to move forward. Cash transactions may remove some of that lender dependency, but even cash buyers can have funding conditions of their own. A buyer may be using private capital, a line of credit, investment financing, or another funding source that still requires coordination.
This is another reason sellers should ask how the buyer intends to close rather than relying solely on labels such as “cash buyer.”
Assignment May Be Part of the Transaction
In a wholesale transaction, the original buyer may have the right to assign the purchase agreement to another buyer. That means the original buyer transfers their contractual interest to someone else who ultimately completes the purchase, subject to the agreement and applicable law.
The seller should not first discover that possibility at the closing table. If assignment is part of the buyer’s business model, it should be disclosed clearly enough that the seller understands who may ultimately purchase the property and how the transaction works.
In other situations, REWholesalers may decide to close on the property directly rather than assign the contract. Those are different transaction paths, but the seller should understand which possibilities exist before signing.
Communication Matters Most When Something Changes
Most real estate transactions are not perfectly linear. Documents are requested, questions come up, contractors need access, title identifies something unexpected, a closing date may need to move, or an underwriting assumption may need to be revisited.
The quality of a transaction is often revealed by how those moments are handled. A buyer who goes silent when there is a problem creates far more uncertainty than the problem itself. The seller is left wondering whether the transaction is still moving forward, whether they need to make another plan, and whether the buyer ever intended to close.
We believe meaningful changes should be communicated as soon as they are known. That does not guarantee every transaction will close exactly as originally expected, but it gives both sides the ability to make informed decisions. The goal after signing should be to reduce uncertainty as the transaction progresses, not continually introduce new uncertainty.
Sellers Should Know What They Are Responsible for Before Closing
Before closing, the seller may have certain responsibilities under the agreement. That could include maintaining the property in substantially the same condition, keeping utilities on, allowing reasonable access, removing personal property, delivering the property vacant, resolving agreed title issues, or providing certain documents.
Other transactions may allow the seller to leave belongings behind, sell with tenants in place, or transfer the property without making repairs. Those differences should be determined by the actual agreement.
A seller should not assume they must clean out an entire property, make repairs, or prepare it for closing unless they have agreed to do so. The same principle applies to the buyer. Both parties should understand what they are responsible for before the closing date arrives.
The Final Walkthrough Is Usually About Confirming Condition
Shortly before closing, the buyer may conduct a final walkthrough. The purpose is generally to confirm that the property is still in the expected condition and that any obligations due before closing have been completed.
A final walkthrough is not supposed to become an entirely new inspection or an opportunity to reopen every part of the transaction. If the property is being sold as-is, the buyer should already understand the condition they agreed to accept. The walkthrough is generally about confirming that something significant has not changed between the original evaluation and closing.
Closing Is Where Ownership Actually Transfers
The transaction is not complete until the required documents are signed, the closing conditions are satisfied, and ownership is transferred according to the closing process in that state.
At closing, the seller typically signs the deed and other required documents. Existing mortgages, liens, taxes, commissions where applicable, and other agreed expenses are accounted for on the settlement statement. The buyer provides the required funds, and the seller receives the proceeds due after those obligations are paid.
Depending on the jurisdiction and the closing process, funds may be delivered by wire, check, or another approved method. Once the transaction is properly funded and completed, ownership transfers to the buyer. That is the point where the sale is actually finished.
A Good Transaction Should Become Clearer After Signing, Not More Confusing
The period between contract and closing can involve a lot of moving parts, but the seller should not feel as though the process becomes more mysterious once the offer is accepted. By that point, the seller should know who the buyer is, what still needs to be verified, how long due diligence lasts, where earnest money is being held, what the expected closing date is, whether the agreement can be assigned, and who is handling the closing.
There may still be questions and unexpected issues because real estate transactions have too many variables for every detail to be known in advance. What matters is that the major steps are understandable and that communication continues as the transaction moves forward. A seller should be able to ask, “What still has to happen before this is actually a closed deal?” and receive a clear, specific answer.
Transparency should not suddenly appear after the agreement is signed. The major parts of the transaction should already be understandable beforehand, and the process should become clearer as information is confirmed. Accepting an offer is the moment the parties agree to move forward, but the work that follows is what carries that agreement to the closing table. When that process is handled well, the seller is not left wondering what is happening next. They can see how the transaction is progressing and what remains before the property is officially sold.
LET’S SEE IF IT’S A FIT
Have a Property You Want Us to Look At?
Tell us what you have and what you’re trying to accomplish. We’ll review the property, look at the situation, and let you know whether it appears to be something we can help with.
No obligation. Just a conversation.
i
Educational Notice:
The information provided on REWholesalers.com is for general educational and informational purposes only. It is not intended to constitute legal, tax, financial, investment, lending, real estate brokerage, or other professional advice. Real estate laws, regulations, practices, and transaction requirements vary by state and may change over time. You should consult the appropriate licensed or qualified professional regarding your specific property, transaction, or circumstances. REWholesalers does not create an agency, fiduciary, attorney-client, lender-borrower, or advisory relationship through the publication of this content.
Any references to assignments, direct purchases, disclosures, or transaction structures are general in nature and may be subject to state-specific laws, licensing requirements, contractual terms, and closing procedures.